
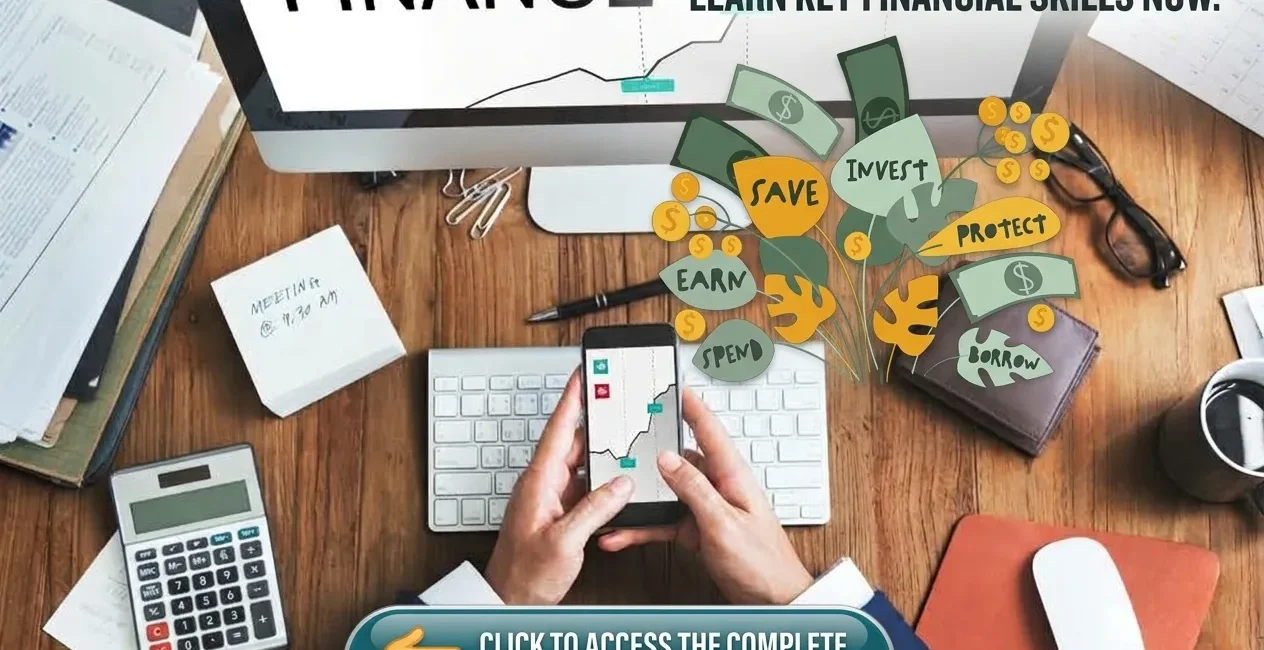
Financial literacy is the ability to understand and use money skills such as budgeting, saving, investing, borrowing, and protecting against risk to make confident decisions about your finances. In simple terms, it is knowing how money works so you can make it work for you.
If you have ever wondered why some people build wealth steadily while others struggle despite good incomes, the answer is rarely luck. More often, it comes down to financial literacy. This guide explains what financial literacy means, why it matters, and exactly how to build it, step by step, even if you are starting from zero.
Key takeaways (quick answers)
- Financial literacy is the knowledge and skill to manage money: budget, save, invest, handle debt, and plan for the future.
- It matters because it reduces stress, helps you avoid costly mistakes, and compounds into real wealth over time.
- The core pillars are budgeting, saving, debt management, credit, investing, insurance, and retirement planning.
- You can build financial literacy for free with trusted resources, a simple budget, and a few consistent habits.
- Start small: track spending, build a starter emergency fund, and automate your savings.
What Is Financial Literacy?
Financial literacy means having the knowledge, skills, and confidence to make smart money decisions. According to Investopedia’s definition of financial literacy, it covers the ability to use skills like personal financial management, budgeting, and investing effectively.
Put differently, financial literacy answers practical questions:
- How much of my income should I spend, save, and invest?
- What is the real cost of this loan or credit card?
- How do I prepare for emergencies and retirement?
- How do I tell a good investment from a scam?
International bodies treat it as a core life skill. The OECD promotes financial education worldwide, while the World Bank links financial capability to economic inclusion. Meanwhile, research groups such as the Global Financial Literacy Excellence Center study how financial knowledge shapes real-world outcomes.
Financial Literacy vs. Financial Education vs. Financial Capability
These terms overlap, yet they are not identical.
| Term | Meaning | Simple Example |
|---|---|---|
| Financial literacy | Knowing and understanding money concepts | Understanding how interest works |
| Financial education | The process of learning those concepts | Taking a budgeting course |
| Financial capability | Applying knowledge consistently in real life | Actually sticking to your budget |
The goal is not just to know. The goal is to act. Therefore, true financial literacy combines knowledge, skill, and behavior.
Why Financial Literacy Is Important
Money touches every part of life. Consequently, why financial literacy is important becomes clear once you see what is at stake.
1. It Reduces Financial Stress
Money worries are among the most common sources of anxiety. When you understand your numbers, uncertainty shrinks. Organizations such as Money and Mental Health highlight the strong connection between financial strain and emotional wellbeing.
2. It Helps You Avoid Expensive Mistakes
A single misunderstanding, such as only paying the minimum on a credit card, can cost thousands over time. The Consumer Financial Protection Bureau (CFPB) publishes plain-language guides precisely because many costly errors are avoidable.
3. It Builds Wealth Through Compounding
Compound interest rewards early, consistent action. Someone who understands this starts investing sooner, and time does much of the heavy lifting.
4. It Protects You From Scams and Fraud
Financially literate people ask better questions. They recognize red flags like guaranteed returns or high-pressure sales tactics. The Federal Trade Commission and ReportFraud.ftc.gov offer tools to spot and report scams, while the SEC’s Investor.gov helps you check whether an investment professional is registered.
5. It Strengthens Communities and Economies
Households with strong money skills are more resilient during recessions. Likewise, financially capable citizens support stronger local economies. Global surveys, including the S&P Global FinLit Survey, have found that only about one in three adults worldwide demonstrates basic financial literacy. Clearly, there is enormous room to improve.
6. It Opens Doors to Opportunity
Good credit, healthy savings, and low debt make it easier to buy a home, start a business, or change careers. If entrepreneurship interests you, see our guide on INTERNAL: business ideas article for ways to put your skills to work.
The 7 Pillars of Financial Literacy
Think of financial literacy as a house built on seven pillars. Strengthen each one, and the whole structure becomes stable.
Pillar 1: Budgeting and Cash Flow
A budget is simply a plan for your money. It shows what comes in, what goes out, and what is left.
A popular starting framework is the 50/30/20 rule:
| Category | Share of After-Tax Income | Examples |
|---|---|---|
| Needs | 50% | Rent, groceries, utilities, transport |
| Wants | 30% | Dining out, streaming, hobbies |
| Savings and debt payoff | 20% | Emergency fund, investing, extra debt payments |
Adjust the percentages to your situation. The rule is a guide, not a law. If you live in a high-cost city, needs may take more than half. That is fine, as long as you plan deliberately.
For official budgeting tools and worksheets, visit MyMoney.gov and the CFPB’s consumer tools.
Pillar 2: Saving and Emergency Funds
An emergency fund is money set aside for surprises, such as medical bills, car repairs, or job loss.
How much should you save?
- Starter goal: a small buffer to cover minor emergencies.
- Standard goal: three to six months of essential expenses.
- Higher goal: more if your income is irregular or you support dependents.
Keep this money in a safe, accessible account. In the United States, deposits at banks are insured through the FDIC, and credit union deposits through the NCUA, within standard limits. Always confirm coverage rules for your country and account type.
A sinking fund is another smart tool. It lets you save gradually for known future expenses, like holidays, insurance premiums, or annual subscriptions.
Pillar 3: Debt Management
Not all debt is equal. Mortgages or student loans may carry lower rates and can build long-term value. By contrast, high-interest credit card balances quietly drain your wealth.
Understand the true cost of borrowing by learning what APR means. Then choose a payoff strategy:
- Debt snowball: pay off the smallest balance first for quick psychological wins.
- Debt avalanche: pay off the highest interest rate first to minimize total interest.
Which is better? Mathematically, the avalanche usually saves more money. Behaviorally, the snowball can keep you motivated. The best method is the one you will actually follow.
Pillar 4: Credit and Credit Scores
Your credit score influences loan approvals, interest rates, and sometimes even rental applications. The widely used FICO model weighs five factors:
| Factor | Approximate Weight |
|---|---|
| Payment history | 35% |
| Amounts owed (credit utilization) | 30% |
| Length of credit history | 15% |
| New credit | 10% |
| Credit mix | 10% |
You can learn more about scoring at myFICO. Meanwhile, U.S. residents can check their reports for free at AnnualCreditReport.com. Review your credit report regularly to catch errors and signs of identity theft.
Quick tips to build good credit:
- Pay every bill on time.
- Keep card balances low relative to limits.
- Avoid opening many accounts at once.
- Keep older accounts open when practical.
Pillar 5: Investing
Saving protects your money. Investing grows it. Because of inflation, cash left idle slowly loses purchasing power.
Beginners often start with index funds, which hold a broad basket of stocks or bonds at low cost. This approach spreads risk through diversification, meaning you avoid putting all your money into one asset.
Before investing, know your risk tolerance. That is how much volatility you can handle emotionally and financially. Your time horizon matters too. Money needed in two years should be treated differently from money needed in thirty.
To learn more, explore:
- Investor.gov for beginner-friendly investor education.
- FINRA’s investor resources for protecting yourself in the market.
- Vanguard’s education hub and Fidelity’s Learning Center for broker-provided guides.
- The community at Bogleheads for long-term, low-cost investing philosophy.
Important: This article is educational and is not personalized financial advice. Consider speaking with a licensed professional for decisions specific to your situation.
Pillar 6: Insurance and Risk Protection
Insurance transfers large, unpredictable risks to a provider. Common types include health, auto, home or renters, disability, and life insurance.
The principle is simple. Insure against losses that would be financially devastating, not minor inconveniences. Compare policies carefully and review them yearly. Consumer comparison sites like NerdWallet and Bankrate can help you understand options before you buy.
Pillar 7: Retirement and Long-Term Planning
Retirement feels distant, yet starting early is the biggest advantage you can give yourself. Learn about employer plans such as the 401(k) and individual accounts like the Roth IRA. If your employer offers a matching contribution, capturing the full match is often considered one of the easiest “free money” wins available.
U.S. readers can estimate future benefits through the Social Security Administration and learn about tax rules at the IRS. Everyone else should check their national pension and tax authority.
To see how all pillars fit into a bigger roadmap, read our companion guide: INTERNAL: financial planning article.
10 Steps to Improve Your Financial Literacy
Wondering how to improve financial literacy without feeling overwhelmed? Follow these ten steps in order.
Step 1: Calculate Your Net Worth
Your net worth is what you own (assets) minus what you owe (liabilities). It is your financial starting line. Do not judge the number. Simply record it, then track it every few months.
Step 2: Track Every Expense for 30 Days
You cannot manage what you do not measure. For one month, record every purchase. Use a notebook, spreadsheet, or a budgeting tool. Looking for a tech-assisted option? See our breakdown in INTERNAL: personal finance app article.
Step 3: Create a Realistic Budget
Using your tracked data, build a budget with the 50/30/20 framework or a zero-based approach, where every dollar has a job. Review it monthly and adjust.
Step 4: Build a Starter Emergency Fund
Begin with a small, achievable target. Then grow it toward three to six months of expenses. Automate transfers so saving happens without willpower.
Step 5: Understand and Attack High-Interest Debt
List every debt with its balance, interest rate, and minimum payment. Pick the snowball or avalanche method. Meanwhile, pay at least the minimum on all accounts so you avoid penalties.
Step 6: Learn the Basics of Credit
Check your credit report, understand your score factors, and set up automatic payments to avoid late fees. Small, consistent actions have an outsized impact.
Step 7: Start Investing Early, Even Small Amounts
Time matters more than amount. The Rule of 72 offers a quick mental shortcut: divide 72 by your annual return to estimate how many years it takes your money to double. At a 6% return, money doubles in roughly 12 years. At 8%, roughly 9 years.
Step 8: Pay Yourself First
The pay yourself first principle means saving before spending. Set up automatic transfers on payday so your future self gets paid before anyone else.
Step 9: Learn From Trusted, Free Sources
Choose courses and books from reputable organizations. For example, Khan Academy’s financial literacy lessons are free and beginner-friendly. Additionally, the FDIC’s Money Smart program offers free modules for adults and young people.
Step 10: Review and Improve Every Quarter
Set a recurring calendar reminder. Every three months, check your budget, debts, savings rate, and investments. Celebrate progress. Adjust where needed. Financial literacy grows through repetition.
Financial Literacy for Different Life Stages
Your priorities shift as life changes. Here is how to focus your efforts.
Students and Young Adults (18-25)
- Build the habit of budgeting on a limited income.
- Learn how student loans and interest work before borrowing.
- Open a first bank account and start a small savings habit.
- Build credit responsibly with on-time payments.
Early Career (25-35)
- Capture any employer retirement match.
- Build a full emergency fund.
- Pay down high-interest debt.
- Begin automated investing in diversified funds.
Mid-Career and Families (35-50)
- Review insurance coverage as dependents increase.
- Plan for education costs and housing goals.
- Increase retirement contributions as income grows.
- Create or update a will and beneficiary designations.
Pre-Retirement and Retirement (50+)
- Estimate retirement income needs and benefits.
- Shift gradually toward lower-risk allocations when appropriate.
- Understand healthcare and long-term care costs.
- Plan withdrawals to manage taxes efficiently.
Entrepreneurs and Freelancers
Irregular income demands extra discipline. Separate personal and business accounts, set aside money for taxes, and hold a larger emergency buffer. If you are exploring self-employment, our guide on INTERNAL: business ideas article can help you find a model that fits your skills.
Common Money Mistakes to Avoid
Even informed people slip. Watch out for these frequent errors.
- Living without a budget. Without a plan, spending expands to fill income.
- Carrying credit card balances. High interest erases investment gains.
- Skipping the emergency fund. One surprise bill can spiral into debt.
- Waiting to invest. Delay costs you years of compounding.
- Chasing hot tips. Social media hype is not a strategy. Check claims with Investor.gov first.
- Ignoring inflation. Money that does not grow loses real value.
- Lifestyle inflation. Raising your spending with every raise prevents wealth building.
- Not reviewing statements. Errors and fraud can hide in plain sight.
- Neglecting insurance. One major event can undo years of progress.
- Making emotional decisions. Panic-selling during market drops locks in losses. Stay anchored to your plan.
Best Free Financial Literacy Resources
You do not need to pay for a good money education. Start with these trusted, mostly free sources.
| Resource | Best For | Link |
|---|---|---|
| CFPB | Consumer protection, loans, credit | consumerfinance.gov |
| MyMoney.gov | U.S. government financial education hub | mymoney.gov |
| Investor.gov | Investing basics and scam checks | investor.gov |
| FDIC Money Smart | Free modules for all ages | fdic.gov/money-smart |
| Khan Academy | Beginner video lessons | khanacademy.org |
| FINRA Investor Education | Safe investing and fraud awareness | finra.org/investors |
| NEFE | Nonprofit financial education | nefe.org |
| Jump$tart Coalition | Youth financial education | jumpstart.org |
| Practical Money Skills | Games and tools for families | practicalmoneyskills.com |
| MoneyHelper (UK) | UK money guidance | moneyhelper.org.uk |
| MoneySmart (Australia) | Australian money guidance | moneysmart.gov.au |
| The Balance | Plain-English personal finance articles | thebalancemoney.com |
Beyond websites, consider reading widely. Books, podcasts, and newsletters on personal finance can deepen understanding, but always cross-check bold claims with official sources like the SEC and the Federal Reserve.
Teaching Financial Literacy to Kids and Teens
Financial habits form early. Parents and teachers can make a lasting difference with simple, age-appropriate lessons.
Ages 5-8: Money basics
- Use a clear jar system: save, spend, share.
- Explain that money is earned, not magically available.
Ages 9-12: Choices and trade-offs
- Give a small allowance and let them make (low-stakes) mistakes.
- Introduce goal-setting, such as saving for a toy over several weeks.
Ages 13-17: Real-world skills
- Open a youth savings account together.
- Walk through a family budget, bills, and how interest works.
- Discuss online scams, subscriptions, and the true cost of credit.
For ready-made lessons, check Practical Money Skills, the Jump$tart Coalition, and Khan Academy. Consistent conversations at home often matter more than any single lesson.
Financial Literacy Self-Check
How strong is your foundation? Answer yes or no.
- I know my monthly income and expenses.
- I have a written budget I review regularly.
- I have an emergency fund, even a small one.
- I know the interest rate on every debt I owe.
- I pay bills on time, ideally automatically.
- I have checked my credit report this year.
- I contribute regularly to a retirement or investment account.
- I can explain compound interest and inflation in my own words.
- I have appropriate insurance coverage.
- I review my finances at least quarterly.
Scoring:
- 8-10 yes: Excellent. Keep refining and teaching others.
- 5-7 yes: Solid base. Focus on the gaps.
- 0-4 yes: Great news: you have clear, high-impact next steps. Start with Steps 1-4 above.
Frequently Asked Questions
What is financial literacy in simple words?
Financial literacy is knowing how to manage money well. It includes budgeting, saving, borrowing wisely, investing, and planning for the future so you can make confident choices with your finances.
Why is financial literacy important?
Financial literacy helps you avoid debt traps, build savings, protect against fraud, and reach long-term goals. It reduces stress and increases your control over your future.
What are the main components of financial literacy?
The main components are budgeting, saving, debt management, credit, investing, insurance, and retirement planning. Together, they cover earning, spending, growing, and protecting money.
How can I improve my financial literacy quickly?
Track your spending for 30 days, create a basic budget, build a starter emergency fund, and spend a few minutes each week learning from trusted sources like the CFPB, Investor.gov, or Khan Academy.
At what age should you learn financial literacy?
The earlier, the better. Children can learn simple saving and spending ideas from around age five. Nevertheless, it is never too late to start. Adults at any age can benefit immediately.
What is the difference between financial literacy and financial education?
Financial education is the learning process, such as courses or workshops. Financial literacy is the resulting knowledge and skill. Financial capability goes one step further: applying that knowledge in daily life.
Is financial literacy taught in schools?
It depends on the country, state, and school. Many regions are expanding requirements, but coverage still varies widely. As a result, learning independently or at home remains valuable.
How does financial literacy help build wealth?
It guides you to spend less than you earn, avoid high-interest debt, invest consistently, and let compound growth work over time. Small, repeated good decisions add up.
Can I become financially literate for free?
Yes. Government sites, nonprofits, libraries, and platforms like Khan Academy offer high-quality lessons at no cost. The key is consistency, not spending.
What is a good first step toward financial literacy?
Calculate your net worth and track your expenses for one month. These two actions show exactly where you stand and what to fix first.
Financial literacy is not about being a math genius or earning a huge salary. It is about understanding a handful of principles and applying them consistently. Build a budget. Save before you spend. Manage debt carefully. Protect your credit. Invest early and patiently. Review your plan often.
Start today with one small action. Track this week’s spending, open a savings account, or read one lesson from Khan Academy or MyMoney.gov. Then keep going. Over the years, those small steps compound into security, freedom, and real choice.
Ready for the next step? Continue with our guides on INTERNAL: financial planning article and INTERNAL: personal finance app article. Bookmark this page, share it with someone who would benefit, and revisit it each quarter as you grow.

The Seecom is your trusted source for unbiased reviews, expert analysis, and comprehensive comparisons to help you choose with confidence.

Personal Finance: The Complete Guide to Managing Your Money
Financial Planning